
Use editorial reviews and official sources to verify current plans, networks, costs, and availability.
Best fit if you want integrated, coordinated care and don't mind staying in-network
Use these points as a research starting point, then verify the exact plan, service area, network and current plan documents that apply to you.
Only available in a handful of states — check the map below before shopping
Highest-rated carrier in this directory for member satisfaction
Kaiser Permanente plan overview
Browse coverage details, plan structure, cost and quality evidence, and the points worth verifying before you compare options.
Kaiser Permanente health insurance review 2026: Our independent verdict
Bottom line: Kaiser Permanente deserves serious consideration if you live within one of its local service areas and prefer an integrated system that connects the health plan, doctors, hospitals, pharmacy and records. It is less attractive when your first priority is unrestricted access to independent out-of-network specialists or you frequently live far from a Kaiser service area. Its distinctive operating model matters more than a generic star rating.
This review primarily evaluates 2026 individual and family Affordable Care Act (ACA) Marketplace coverage. Kaiser Permanente is not one nationwide policy: regional Kaiser Foundation Health Plan legal entities offer different contracts, networks and prices. Medicare Advantage, Medicaid and employer arrangements are discussed separately and must not be substituted for an ACA plan. We reviewed official Kaiser plan materials, the 2026 NCQA announcement, federal Marketplace guidance and independently published premium comparisons through October 22, 2026.
Our verdict is conditional rather than a fabricated numerical customer score. First check whether a suitable Kaiser plan and its care network serve your ZIP code, then compare its real annual costs and access to the clinicians you expect to use. A highly rated plan is not a good fit if your doctors are not in its network or your travel needs conflict with the contract.
What Kaiser Permanente is: Integrated coverage and health care
Kaiser Permanente is an integrated system comprising Kaiser Foundation Health Plans, Kaiser Foundation Hospitals and independent Permanente Medical Groups. The nonprofit health plans and hospitals are not the same legal organizations as the physician groups. Covered California's explanation describes that organizational arrangement. Kaiser should not be confused with a large national PPO carrier offering any licensed clinician at a common in-network rate.
In practice, the integrated model can help coordinate primary care, referrals, specialist notes, labs, imaging and prescriptions within a connected system. A patient with regular follow-up appointments may appreciate not having to relay results between multiple unrelated organizations. The trade-off is a more defined provider network; availability and specialist choice vary by market, and a separate independent hospital may not participate in the purchased plan.
For the exact contract, look for Kaiser Foundation Health Plan, Inc. or a named regional Kaiser Foundation Health Plan issuer in the plan's Evidence of Coverage (EOC) and Summary of Benefits and Coverage (SBC). The legal issuer and network are the entities to verify—not just the Kaiser Permanente logo.
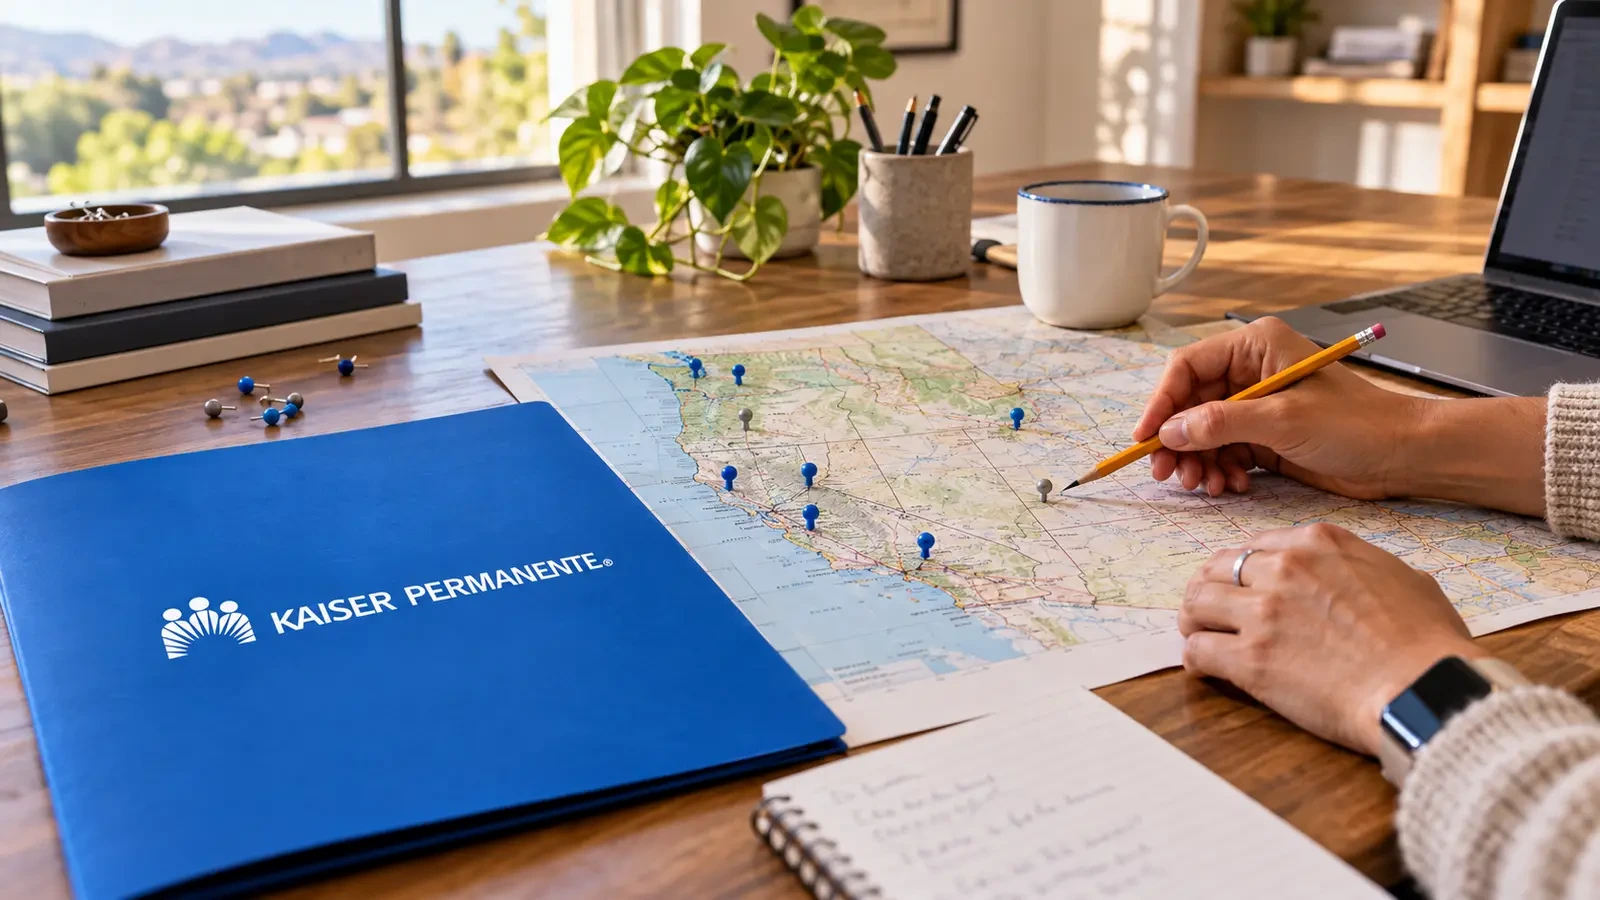
Kaiser Permanente service-area map: Eight states plus Washington, D.C.
For individual and family plan service-area reference, Kaiser's own member guidance identifies California, Colorado, Georgia, Hawaii, Maryland, Oregon, Virginia and Washington, plus the District of Columbia. The map on this page represents these broad markets; it does not promise availability in every county or ZIP code. The Oregon/Washington, Northern/Southern California and Mid-Atlantic plan and provider footprints have important internal boundaries.
Kaiser can participate through different regional entities: California and Hawaii under Kaiser Foundation Health Plan, Inc.; Colorado and Georgia through separate regional issuers; Northwest coverage in Oregon and selected Washington counties; Washington through Washington-specific entities; and Maryland, Virginia and D.C. through the Mid-Atlantic entity. Kaiser's official state-by-state legal-issuer notice provides this breakdown. A county in one of those states may nevertheless have no applicable Kaiser Marketplace offering.
For an authoritative answer, enter your own ZIP code at HealthCare.gov or the designated state Marketplace, then open the local plan's provider directory and SBC. At this October 2026 update, 2026 enrollment generally requires a qualifying Special Enrollment Period; the federal Marketplace explains possible eligibility through its coverage eligibility screener. Do not assume a future plan-year expansion is already available.
ACA plan types: HMO, copay, deductible, HSA and virtual care
Kaiser is best known for its tightly coordinated HMO-style coverage, but consumers should compare the full plan design rather than treating 'Kaiser' or 'HMO' as a complete benefit description. Its official individual and family shopping guide describes copay plans (higher monthly premiums can accompany simpler visit copays), deductible plans (some care may be subject to paying toward the deductible first), and certain virtual plans that change the relative cost of virtual versus in-person primary care. Some local deductible designs may be HSA-eligible, but HSA eligibility must be confirmed for the exact contract and year.
Bronze, Silver, Gold and sometimes Platinum describe general actuarial cost-sharing levels; they do not tell you which doctors participate. A Bronze and Gold Kaiser plan may use similar core care infrastructure yet create different bills for office visits, specialists, prescriptions and hospital services. The 2026 plan materials are available through regional document libraries, such as Kaiser's Colorado 2026 individual/family library.
Practical test: compare the actual contract's PCP selection/referral terms, procedure authorization, outpatient and inpatient costs, emergency and urgent care conditions, lab charges and prescription formulary. A plan family that looks economical on the monthly premium may shift more spending to the patient at the time of care.
Kaiser Permanente premiums in 2026: Compare age-specific evidence
Forbes Advisor's 2026 company comparison publishes sampled unsubsidized ACA premiums. Its Kaiser Silver examples are approximately $442/month at age 30, $498 at age 40, $696 at age 50 and $1,057 at age 60. Those are analytical benchmark averages over the publication's sampled plans, not offers obtainable by every customer in a common ZIP code. The structured charts below use the same expressly labeled Silver age basis.
Regional rates can vary substantially by county, age, household members, plan design and permitted tobacco-rating rules. Applicable premium tax credits can reduce what an eligible Marketplace household actually pays. The company's official California 2026 rate guide explicitly keys premiums to age and rating area—an illustration of why a nationwide average is not a personalized quote. Use federal premium-tax-credit guidance for eligibility and the actual Marketplace application for your net premium.
Bronze, Silver, Gold and Platinum: Kaiser 2026 tier comparison
Forbes Advisor's 2026 Kaiser sample at age 40 is $404 Bronze, $498 Silver, $542 Gold and $630 Platinum per month, before subsidies. The table below supplies the equivalent figures for ages 30, 50 and 60. These are useful directional comparisons for a budget—not a quotation for four simultaneously available contracts in the same county.
Bronze generally favors lower premiums if you expect relatively little nonpreventive care; Gold or Platinum can become preferable if more predictable cost-sharing offsets the higher premiums. Silver deserves special attention for applicants eligible for Marketplace cost-sharing reductions (CSR): qualifying enhanced cost-sharing is generally available only when enrolled in an eligible Silver Marketplace plan. See HealthCare.gov's CSR explanation.
Do not infer lower overall annual cost solely from color. Compare annual premium after credits, deductible, maximum in-network out-of-pocket amount, ordinary specialist use, drugs and expected imaging or hospitalization. A Gold plan with a less suitable clinic or drug list may perform worse for your household than an appropriate Silver plan.
Deductibles, copays and out-of-pocket maximums
There is no defensible single national 2026 Kaiser deductible covering the different regional ACA issuers and metal tiers. Some Kaiser copay products advertise simplified office-visit expenses, while deductible products generally require more cost sharing before certain benefits are paid. The individual and family plans page says some visits or prescriptions can have specified copays even before a deductible is met, depending on the plan. Your SBC—not an average deductible on an unrelated review—controls.
The in-network maximum out-of-pocket (MOOP) is important for a household facing a high-use medical year. Premiums, noncovered services, and certain outside-network charges generally do not count the same way as covered in-network cost sharing. Ask for the individual and family deductible/MOOP structure, and whether a requested specialist, imaging center, surgery center or pharmaceutical is covered at the expected tier.
To compare plans fairly, model two scenarios: a low-use year of preventative care plus two PCP appointments, and a higher-use year with specialist visits, tests and one hospital episode. Include the pharmacy spend in both. The Kaiser cost guide explains how premiums, copays, coinsurance and deductibles interact.
Doctors, specialists and hospitals: Network trade-offs
A frequent reason to choose Kaiser is the connected system; a frequent reason not to choose it is a desire for a particular independent doctor or hospital outside that system. Its network guide states that many plans do not cover routine outside-network care except defined situations such as emergencies. It also directs members to verify doctors, hospitals, pharmacies, labs and specialists against the relevant directory.
Confirm the physician's name and location, the specialty, hospital privileges and availability for new patients. Ask whether the exact plan requires a PCP referral or prior authorization for the contemplated procedure. If you already have an oncologist, a rare-disease specialist or an established mental-health clinician, do not assume continuity before checking the participating-provider rules and any applicable transition-of-care provisions.
For someone who values a broad independent-provider PPO, Kaiser HMO's limited routine out-of-network flexibility may be a decisive disadvantage. Certain Kaiser regional employer or special-plan products can have PPO-style features; do not assume those features apply to an ACA HMO.
Travel, urgent care and emergencies outside a Kaiser area
A connected local network is not identical to nationwide routine-care access. Kaiser's travel-care guidance describes options for urgent and emergency care away from a Kaiser region and warns that virtual care across state lines can be limited by licensing laws. Some travel arrangements involve particular outside provider networks or reimbursement rules and can differ by product.
For a medical emergency, go to the nearest appropriate emergency facility or call 911. For nonemergency travel care, check the actual member handbook first; do not treat the phrase 'Kaiser operates in eight states and D.C.' as a promise that a provider in another Kaiser region is automatically in your plan's routine-care network. Long-term residence elsewhere is a different issue from a temporary trip.
Telehealth, member app, messaging and appointment access
Kaiser's digital system can be a practical benefit for members who prefer to communicate with one care team. Its official telehealth guide describes scheduled phone and video consultations, advice lines, e-visits and secure messaging. Features, charges and availability are subject to region and contract. A virtual-first plan may offer different primary-care cost sharing than a traditional in-person-focused design.
Check what is available outside business hours, whether a particular service is staffed in your region, and whether behavioral-health appointments use the same digital pathway. For a recurring condition, ask if test results, prescriptions and follow-up instructions flow to the same medical record. Digital convenience does not replace a good local specialty network.
Prescription drugs, formulary tiers and pharmacy access
Kaiser plans often coordinate clinicians and pharmacies, but that does not mean all medications have a universal copay. The 2026 California Marketplace formulary illustrates tier restrictions, clinical criteria and potentially different member costs for pharmacy delivery. It is an example from one state and must not be used as the drug list for a different Kaiser region.
Before enrollment, search every maintenance drug and its dosage in the correct plan-year regional formulary. Verify generic versus brand treatment, prior authorization, step therapy, quantity limits, insulin-specific terms when relevant, mail-order eligibility and whether your preferred pharmacy participates. For costly specialty drugs, request the plan's written coverage and out-of-pocket estimate rather than relying on a general 'prescription coverage included' marketing statement.
Preventive care, mental health and other included benefits
Qualified ACA Marketplace plans generally cover federally required essential health benefits, which include preventive services, prescription drugs, mental-health/substance-use treatment, laboratory services, emergency services and other categories under applicable rules. Many recommended preventive services are covered without patient cost-sharing when eligibility and in-network conditions apply. This is an ACA framework, not a guarantee that every appointment, treatment, provider or medication is free.
Kaiser's integrated record system may support regular screenings, chronic-condition follow-up and coordinated behavioral-health referrals. Yet appointment lead time, local specialty capacity, provider assignment and telehealth availability are regional realities that quality ratings alone cannot answer. Read the EOC's limits on outpatient therapy visits, authorization, rehabilitation, fertility services, dental and vision coverage, and confirm whether any additional benefits require optional riders or separate products.
2026 NCQA ratings: Strong results, but not one national plan score
The October 2026 Kaiser announcement citing the National Committee for Quality Assurance (NCQA) says nine of the eighteen health plans nationwide that received a top 5.0/5 rating in 2026 were Kaiser Permanente plans. The release says Kaiser's commercial, Medicare and Medicaid plans were highest-rated or tied highest within each region they served. Its cited top commercial examples include Northern California and the Mid-Atlantic area; Hawaii's commercial, Medicare and Medicaid plans were each rated 4.5/5.
That is meaningful quality evidence, but the denominator is rated health-plan contracts, not one nationwide Kaiser company rating; some of the nine are not ACA plans. To review the exact insurer, product and local quality measures, search the NCQA Health Plan Report Cards. For that reason, ApexTrusted does not assign an unsupported universal Kaiser 2026 NCQA numeric score to the profile.
Forbes Advisor separately gives Kaiser Permanente a 5.0/5 editorial score in its 2026 comparison. It is a third-party publication's methodology, not a federal regulator's star rating or a verified average of customer reviews. The numbers should not be added together or treated as interchangeable.
Consumer complaints and financial-strength evidence
Regulatory complaint indexes and financial-strength ratings should be matched to the specific licensed insurer, reporting year and coverage line. Because Kaiser operates through regional issuers, an undated brand-wide complaint value can mislead. Although Forbes' insurer review describes relatively low complaint incidence in its analyzed sample, we have not verified a same-year, same-entity NAIC comparator for every Kaiser Marketplace subsidiary. Accordingly, we do not display an invented current national complaint index or a blended corporate financial rating here.
In your state, use the department of insurance's consumer-complaint resources and match the issuer name on the policy. For coverage disputes, keep claim and appeal records, review the explanation of benefits, and check the plan's grievance and external-review rights. A complaint count without enrollment denominator or legal-entity match is not a fair carrier ranking.
Medicare Advantage and Medicaid are separate Kaiser products
Kaiser also offers Medicare Advantage programs in relevant markets and Medicaid arrangements in participating regions. Those products may have different eligibility rules, drug benefits, provider networks and rating systems from individual ACA Marketplace coverage. Kaiser published separate CMS 2026 Medicare Star Rating results. A Medicare star score cannot be assigned to a 2026 ACA policy, and a Medicare service-area update does not automatically expand Kaiser's individual ACA footprint.
Medicare shoppers should use Medicare Plan Compare for county-specific plans, provider access, covered prescriptions and annual benefits. Medicaid shoppers should check eligibility and the actual state-managed or Medicaid managed-care contract. This review's age/metal-price charts apply to ACA research, not Medicare premiums.
Kaiser vs. Blue Cross Blue Shield, Ambetter and Molina: 2026 comparison
In Forbes Advisor's 2026 unsubsidized Silver sample for age 40, Kaiser is approximately $498/month, Molina $503, Ambetter $523 and the Blue Cross Blue Shield group $654. At age 40 in the Bronze sample, the figures are respectively $404, $457, $437 and $501. These are published sampled averages, not quotes for identical benefits, markets or ZIP codes. BCBS itself encompasses many distinct licensed insurers and networks.
The substantive choice is often as important as price: Kaiser emphasizes coordinated regional care; a given local BCBS plan may offer a different provider model; an Ambetter or Molina offering may use a narrower or differently structured ACA network depending on the county. A $20 average difference means little if the cheaper contract excludes an important physician or medication. Compare the exact county, subsidy status, local hospital and total annual out-of-pocket scenarios.
Best fit, drawbacks and a seven-point enrollment checklist
Kaiser may fit you if: you live within its actual participating counties, value integrated primary/specialty/pharmacy coordination, are comfortable choosing from a defined provider system, want digital follow-up, and find a local plan whose complete costs are competitive. It may be a weaker fit if you regularly seek uncontracted specialists, travel for long stretches outside a Kaiser area, or need a hospital outside its contracted network for scheduled care.
- Confirm the ZIP code: locate an actual 2026 or 2027 offer in your official state Marketplace.
- Identify the issuer: note the regional Kaiser Foundation Health Plan legal name and exact network.
- Verify doctors: check each desired doctor and hospital with both the plan directory and provider office.
- Review prescriptions: confirm each drug, strength, tier, pharmacy, prior-authorization and mail-order rule.
- Calculate total costs: include twelve after-credit premiums, expected copays, deductibles and an emergency/high-use scenario.
- Check exceptions: specialist referrals, out-of-network care, emergencies, travel and care across state lines.
- Save documents: keep the SBC, EOC, formulary, provider-directory screenshot and policy effective date.
Frequently asked questions about Kaiser Permanente
Is Kaiser Permanente good health insurance in 2026?
It can be, especially when the local network fits your doctors and you value coordinated care. Kaiser's 2026 NCQA plan-level results are a positive quality indicator, but the right policy depends on network, out-of-pocket costs and individual circumstances. No plan-level score guarantees a particular patient experience.
Does Kaiser Permanente cover all 50 states?
No. For individual/family service-area reference, Kaiser lists eight states—California, Colorado, Georgia, Hawaii, Maryland, Oregon, Virginia and Washington—plus Washington, D.C. Not every county in those markets is served, and emergency/travel arrangements are different from routine local coverage.
Can I see non-Kaiser doctors?
For many HMO policies, routine nonemergency care outside the designated network is generally restricted unless specific contractual exceptions or authorization apply. Emergency care is different. Check the purchased plan's EOC and the travel-care rules; some separate non-ACA products have different provider flexibility.
How much does Kaiser cost per month?
The Forbes 2026 illustrative unsubsidized Silver sample is approximately $498 at age 40, but actual rates depend on location, age, family, policy and eligible tax credits. Use the official Marketplace quote, not this national study average, for a decision.
Does Kaiser have PPO or HSA plans?
Kaiser offers a variety of regional and employer products; its Marketplace focus is HMO-style coverage, while certain deductible arrangements may meet HSA eligibility rules. Some other Kaiser product lines offer expanded provider choice. Do not infer that an employer PPO feature or HSA account applies to an ACA policy; verify the actual document.
Is Kaiser Medicare Advantage the same as Kaiser Marketplace insurance?
No. Medicare Advantage operates under separate eligibility, benefits, geographic contracting and CMS star ratings. Marketplace metal tiers and sample premiums in this review must not be used for a Medicare decision.
How ApexTrusted reviewed Kaiser Permanente: Sources and data boundaries
Our process distinguishes (1) official regional insurer and plan materials, (2) federal Marketplace rules, (3) independent NCQA plan-contract ratings, and (4) externally published price and editorial score research. We reviewed the official Kaiser individual/family shopping and legal-issuer pages, sample 2026 regional rate/EOC/formulary documents, NCQA 2026 company release and report-card directory, HealthCare.gov eligibility and financial-assistance guidance, and the Forbes Advisor 2026 comparative dataset. Direct references are listed in the source panel below.
Interpretation safeguards: state-map pins are broad market references, not verified every-county availability; illustrative average premiums are unsubsidized studies, not personalized offers; NCQA is contract-level, Medicare CMS Stars are a different program, and the Forbes 5/5 score is third-party editorial opinion. The photographs are AI-generated editorial illustrations with accurately sourced carrier imagery, not real insurer employees or patient testimonials. We intentionally withhold an unsupported combined Kaiser complaint index, deductible, AM Best score or customer rating.
Updated October 22, 2026. Marketplace contracts, provider participation, rates and enrollment windows change by policy year. Confirm the local official documents before enrollment. This independent editorial analysis is not medical, legal or tax advice and does not claim a relationship with Kaiser Permanente.
Where Kaiser Permanente Is Available
8 states plus Washington, D.C. are listed for individual and family ACA marketplace coverage. Availability still varies by ZIP code and county.
- CACalifornia
- COColorado
- GAGeorgia
- HIHawaii
- MDMaryland
- OROregon
- VAVirginia
- WAWashington
- DCDistrict of Columbia
SourcesKaiser individual/family legal issuer listingKaiser coverage states referenceHealthCare.gov see 2026 plansHealthCare.gov SEP screener
Market Position & Enrollment
Market metrics are source-backed research context. Read the population, date and product scope before comparing values.
Individual/family geographical footprint reference — official Kaiser 2026 guidance
View table
| Area | Status | Critical qualification |
|---|---|---|
| California | Broad regional presence | Southern/Northern region and local ZIP restrictions |
| Colorado | Regional presence | County and plan-specific Marketplace participation |
| Georgia | Regional presence | Metropolitan/service-area limits |
| Hawaii | Regional presence | Island, provider and plan differences |
| Maryland, Virginia, D.C. | Mid-Atlantic presence | Local county/ZIP and contract determine eligibility |
| Oregon | Northwest presence | County-specific availability |
| Washington | Northwest/WA regional presence | Separate Washington and Southwest Washington plan entities |
| National 2026 comparison | 8 states plus D.C. | NOT every county, every ZIP or every insurance line |
How Much Do Kaiser Permanente Plans Cost?
Forbes Advisor's 2026 comparison, accessed October 22, 2026, publishes average unsubsidized ACA monthly premiums. The age chart here is specifically SILVER by age 30/40/50/60; the tier table also distinguishes Bronze, Silver, Gold and Platinum. $498 is age-40 SILVER research benchmark, NOT an actual premium quote or general rate for every age, state, county or policy. Published competitor samples may not come from common ZIP codes or equivalent networks. Official 2026 Kaiser regional rate guides tie rates to age and geography. Premium tax credits/CSR eligibility can materially change net costs. Kaiser deductible, MOOP, HSA and PCP rules require the exact 2026 or 2027 policy documents.
Average cost by age
Average cost by metal tier
| Age | Bronze | Silver | Gold | Platinum |
|---|---|---|---|---|
| Age 30 | $359 | $442 | $481 | $560 |
| Age 40 | $404 | $498 | $542 | $630 |
| Age 50 | $564 | $696 | $757 | $881 |
| Age 60 | $858 | $1,057 | $1,151 | $1,338 |
SourcesForbes Advisor Best Health Insurance Companies of 2026Kaiser Permanente 2026 CA rate chart guideKaiser plan cost guideHealthCare.gov ACA premium tax creditsHealthCare.gov Silver CSR
How Costs Compare
These tables summarize available premium benchmarks or qualitative plan trade-offs, depending on the evidence for this carrier. They are research references, not personalized quotes; verify current plan availability, eligibility and actual costs for your ZIP code.
Age 40, 2026 average unsubsidized ACA premiums — Forbes Advisor research sample
| Company | Bronze/month | Silver/month | Gold/month |
|---|---|---|---|
| Kaiser Permanente | $404 | $498 | $542 |
| Ambetter | $437 | $523 | $556 |
| Molina Healthcare | $457 | $503 | $547 |
| Blue Cross Blue Shield sample | $501 | $654 | $700 |
Kaiser Permanente 2026 Silver monthly benchmark by age
| Age | Sample monthly premium | Scope |
|---|---|---|
| 30 | $442 | Unsubsidized ACA Silver |
| 40 | $498 | Unsubsidized ACA Silver |
| 50 | $696 | Unsubsidized ACA Silver |
| 60 | $1,057 | Unsubsidized ACA Silver |
SourcesForbes Advisor Best Health Insurance Companies of 2026Kaiser Permanente 2026 CA rate chart guideKaiser plan cost guideHealthCare.gov ACA premium tax creditsHealthCare.gov Silver CSR
Plan & Product Metrics
Structured plan-level research metrics. Exact availability and values can vary by market and product.
2026 Kaiser review evidence checkpoints
| Measure | Verified value | Interpretation |
|---|---|---|
| Age 40 Silver sample | $498 per month | Forbes Advisor 2026 unsubsidized ACA study; not a ZIP quote |
| Age 40 Bronze sample | $404 per month | Separate metal tier, not same deductible |
| Age 40 Gold sample | $542 per month | Separate metal tier and cost sharing |
| Age 40 Platinum sample | $630 per month | Availability varies by county |
| NCQA top-scored Kaiser contracts | 9 of 18 national 5-star plans | 2026 NCQA statement via Kaiser; includes different product lines |
| Forbes Advisor editorial rating | 5.0 out of 5 | External publication's evaluation, not consumer satisfaction or CMS |
Kaiser Permanente Product Comparison
Distinct product families have different eligibility, networks, benefits and pricing. Verify the exact product available in your location.
Kaiser individual/family plan design decision aid — official Kaiser descriptions
| Plan design | Potential advantage | Trade-off to inspect |
|---|---|---|
| Copay-based local plan | Predictable visits and fewer deductible surprises for certain care | Higher monthly premium possible; regional availability |
| Deductible-based local plan | Often lower recurring monthly costs | Deductible exposures and service exceptions vary |
| Virtual-oriented local plan | Virtual primary/preventive care may receive preferential cost-sharing | Local telehealth and in-person rules differ |
| HSA-eligible deductible design, where offered | Tax-advantaged HSA may apply if IRS-qualified | Eligibility and benefits must be confirmed in specific contract |
Keep different insurance lines separate
| Line | Intended customer | Ratings / costs that apply |
|---|---|---|
| ACA individual and family | Marketplace eligibility and plan tiers | 2026 metal-tier samples and applicable individual/family NCQA entities |
| Employer coverage | Participating employer group | Contract-specific benefits; not necessarily ACA Marketplace design |
| Medicare Advantage | Medicare-eligible members in listed counties | CMS 2026 Medicare Stars and Medicare.gov plan details |
| Medicaid managed care | State-specific eligible members | State contract and Medicaid-specific measures |
SourcesKaiser individual and family plansKaiser 2026 Colorado plan documentsMedicare.gov plan compare
Benefits & extras listed for Kaiser Permanente
These features can differ by product, service area and plan year. Treat them as review points to confirm in the exact plan documents.
-
Coordinated primary and specialist care Medical group and network participation depend on region and contract
-
Preventive care ACA-required preventive services subject to eligibility and in-network rules
-
Virtual and phone appointments Availability and any cost-sharing vary by local plan
-
Prescription drug coverage Regional formulary, tiers and authorization rules apply
-
Behavioral health Covered category subject to local network and plan conditions
-
Travel urgent and emergency care Specific reimbursement and network terms depend on contract
Benefits and cost sharing vary by plan and location. Check the exact plan's Summary of Benefits and Coverage before making a coverage decision.
SourcesKaiser plan cost guideHealthCare.gov Silver CSRKaiser in-network and out-of-network guideKaiser care outside local areaKaiser telehealth official explainerKaiser 2026 CA Marketplace formulary
How this Kaiser Permanente review was built
Data checked October 22, 2026. Methodology documents scope and limitations; it is not a ranking score.
- Scope
- 2026 individual/family ACA Marketplace plans primarily. 2026 Medicare Advantage CMS Stars and Medicaid are discussed but never merged with ACA coverage or rates.
- Entity
- Kaiser Foundation Health Plan legal issuers differ by region, as do medical networks and hospitals. This is an integrated system, not one uniform national marketplace policy.
- Geography
- Official Kaiser individual/family guidance identifies California, Colorado, Georgia, Hawaii, Maryland, Oregon, Virginia, Washington and D.C. Map references broad regional footprint only, not every county/ZIP.
- Products
- HMO-style core, copay/deductible/virtual plan designs and conditional HSA eligibility come from official Kaiser guidance; eligibility must be verified in local SBC/EOC.
- 2026 prices
- Forbes Advisor's 2026 cross-market unsubsidized ACA samples. Est premium $498 is specifically age-40 Silver sample. Age series specifically Silver; published tier comparison is not a county-based local offer.
- Quality
- Oct 2026 Kaiser announcement reports 2026 NCQA 9 of 18 national 5-star rated contracts, including multiple insurance lines; NCQA plan-specific directory offered for primary verification.
- Editorial rating
- Forbes 5.0/5 is attributed as external opinion, not an ApexTrusted rating or independently surveyed customers.
- Complaints
- No brand-wide current complaint index published without uniform NAIC legal-entity/year/line validation; old unsourced numeric field removed.
- Financial strength
- No insurance-group-wide AM Best rating assigned without entity/product/year match.
- Medicare
- Separate CMS 2026 Medicare star research, not applicable to ACA price/rating fields.
- Benefits/travel/drugs
- Official Kaiser regional materials and HealthCare.gov ACA rules; local contract/formulary controls.
- Images
- Six original AI editorial illustrations with authentic Kaiser current wordmark on independent research materials; they are not real policyholders, clinicians or carrier-sponsored campaigns.
- Evidence reviewed
- October 22, 2026; plan-year changes and enrollment status require direct Marketplace check.
Direct research sources
- Kaiser individual/family legal issuer listingRegional legal entities and county exceptions
- Kaiser coverage states referenceEight states and District of Columbia
- HealthCare.gov see 2026 plansActual ZIP-specific products and price
- HealthCare.gov SEP screenerOctober 2026 enrollment requires applicable eligibility
- Kaiser individual and family plansCopay, deductible and virtual options; region-dependent
- Kaiser 2026 Colorado plan documentsActual plan-year evidence
- Covered California Kaiser business profileCorporate legal structure and integrated practice distinction
- Forbes Advisor Best Health Insurance Companies of 20262026 unsubsidized ACA age and tier data; external 5/5 editorial evaluation
- Kaiser Permanente 2026 CA rate chart guidePublished 2026 rate by age/rating area; not national quote
- Kaiser plan cost guidePremium/deductible/coinsurance basics
- HealthCare.gov ACA premium tax creditsNet costs depend on eligibility
- HealthCare.gov Silver CSRQualifying Silver cost-sharing reductions
- Kaiser in-network and out-of-network guideRoutine provider-network restrictions
- Kaiser care outside local areaEmergency/urgent travel rules and caveats
- Kaiser telehealth official explainerVideo, phone, messaging options and regional restrictions
- Kaiser 2026 CA Marketplace formularyState-specific formulary, not national drug list
- NCQA 2026 Kaiser quality announcement9 of 18 national top-rated contracts; product lines differ
- NCQA health plan report cardsContract-specific quality lookup
- CMS 2026 Medicare Advantage stars KaiserMedicare only; not ACA score
- Medicare.gov plan compareCounty-specific Medicare product verification
Compare other company reviews
Open another review to compare published cost context, plan types, availability and quality signals side by side.
-
 Florida Blue
Read reviewPremium reference See review dataPlan types HMO, EPO, POS, PPO
-
 Highmark
Read reviewPremium reference See review dataPlan types PPO, EPO (local options); Bronze, Silver, Gold
-
 Blue Cross Blue Shield
Read reviewPremium reference $637/moPlan types HMO, EPO, PPO, POS
Questions & customer reviews
Frequently asked questions
Answers to common research questions about Kaiser Permanente.
Is Kaiser Permanente available in my state?
Carrier availability varies by state and county and can change from year to year. Check the official Marketplace and Kaiser Permanente's current service-area tools using your ZIP code before relying on a carrier-level availability claim.
What plan types are usually offered?
Plan types such as HMO, EPO and PPO vary by carrier, state and service area. Use this review as a starting point, then confirm the exact network type in the current plan documents for your ZIP code.
How do I know if I qualify for a subsidy?
Premium tax credits and cost-sharing reductions depend on household income, household size and other Marketplace eligibility rules. Use the official Marketplace application or estimator for household-specific results; this review does not determine eligibility.
Can I switch carriers mid-year?
Generally you can only switch during Open Enrollment, unless you have a qualifying life event (like losing other coverage, moving, marriage, or a new baby) that opens a Special Enrollment Period.
How do I check if my doctor is in-network?
Network coverage varies by specific plan, not just by carrier. Search the carrier's directory using the exact plan and ZIP code, then confirm directly with the provider or pharmacy when possible.
What's the difference between HMO and EPO plans?
An HMO typically requires a referral to see a specialist and limits care to in-network providers. An EPO also limits care to in-network providers but usually does not require a referral.
How do I file a claim or a complaint?
Claims and member complaints are handled through the carrier's plan documents, member portal and customer-service process. For unresolved insurance complaints, your state insurance department can provide the applicable consumer-assistance route.
Is this the same as Medicare or Medicaid?
Medicare and Medicaid are separate government programs with their own eligibility rules. Some carriers, including Kaiser Permanente, may offer separate Medicare or Medicaid products in addition to ACA marketplace coverage; verify program eligibility and local availability through the applicable official program.
Where do I verify current plans and enrollment options?
Use the official Marketplace or the carrier’s current plan-search tools for your ZIP code. ApexTrusted provides editorial review information; any enrollment is handled by the Marketplace, the carrier, or a separately licensed third party you choose to use.
Customer reviews
No reviews yet for this carrier — be the first to share your experience.